Professionals Insurance Online :: News
SHARE

Share this news item!

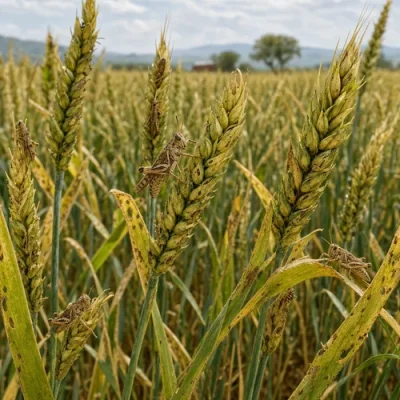
Locust Hatchings Put Crop Risk and Policy Wording in Focus

North-west Victorian reports are a reminder that pest outbreaks can create costs before any claimable loss is clear

Locust Hatchings Put Crop Risk and Policy Wording in Focus?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Fresh reports of Australian plague locust activity in north-west Victoria have added a practical risk-management issue to an already important harvest period.
ABC Rural reported on 17 October 2026 that farmers in parts of the Mallee were concerned about growing locust numbers and the cost of control, while Agriculture Victoria’s October updates show hatchings across listed Mallee locations and surveillance extending into the Wimmera.

The development matters because locust risk rarely fits neatly into one farm decision. It can affect standing crops, pasture, fodder, horticulture, spray programs, labour availability and contractor timing. It can also create uncertainty around who pays for prevention, response and damage after the event. Agriculture Victoria has described the current approach as a shared-responsibility model, with land managers expected to monitor and control their own properties while government agencies provide surveillance, forecasting and advice.

For farm operators, the insurance lesson is not simply whether locust damage is “covered”. Policy responses can vary significantly depending on the type of policy, the insured event, exclusions, notification requirements, evidence of loss and whether the cost relates to prevention, mitigation or actual physical damage. Many farmers will be familiar with crop insurance that responds to named perils such as fire, hail or storm, but pest damage, disease, yield reduction and chemical treatment costs may be treated differently unless the wording specifically provides for them.

The immediate priority is operational: finding hatchings early, acting while locusts are still in a controllable stage, keeping spray records and documenting crop condition before and after any event. From an insurance perspective, those same records can also be useful if a loss is later discussed with an insurer, adviser or broker. Photos, paddock maps, contractor invoices, chemical records, yield evidence and reports made to authorities may help establish timing and scale, even where a policy ultimately does not respond.

Several practical review points stand out for producers in affected or nearby districts:

  • Check whether crop, pasture, hay, grain and stored produce are insured under separate sections or different policies.
  • Review pest, vermin, disease and gradual-damage exclusions before assuming a loss pathway exists.
  • Confirm whether prevention or control costs are treated differently from damage to insured property.
  • Keep clear records of monitoring, spraying, contractor use, reported sightings and yield impacts.
  • Consider whether sums insured still reflect current replacement values for inputs, stored fodder, infrastructure and machinery used in response work.

The current situation is not being described by Agriculture Victoria as a predicted plague, and local conditions may differ sharply between properties. Even so, the hatchings are a timely reminder that farm insurance reviews should account for less dramatic but highly disruptive risks. Pest outbreaks can sit in the grey area between biosecurity management, agronomy, government response and insurance wording, making preparation and documentation just as important as the policy schedule itself.

Published:Thursday, 29th Oct 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

What Rising Insurance Disputes Mean for Income Protection Customers
29 Oct 2026: Paige Estritori
New Zealand’s latest insurance dispute figures are a timely warning for anyone relying on personal cover to protect their household income. The Insurance & Financial Services Ombudsman Scheme reported that, for the year ended 30 June 2026, health insurance became the largest category of disputes it investigated for the first time, with health disputes up 91 percent and 833 dispute investigations completed across all categories. - read more
Why Falling Insurance Rates May Not Flow Evenly to Truck Operators
29 Oct 2026: Paige Estritori
Fresh commercial insurance market data is giving Australian businesses a more favourable pricing backdrop, but truck owners should be cautious about assuming broad rate falls will automatically reduce heavy vehicle premiums. Marsh’s Q3 2026 Global Insurance Market Index, released on 21 October 2026, reported a 12 per cent fall in Pacific commercial insurance rates for the quarter, led by property and supported by strong insurer competition and available capacity. - read more
Why Data Centre Work Is a Different Risk for Tradies
29 Oct 2026: Paige Estritori
Australia’s fast-growing data centre construction market is opening opportunities for electrical, HVAC, fire protection, cabling, fit-out and commissioning trades, but recent insurance industry discussion suggests the risk settings are not always keeping pace with the work. At a recent Australasian Professional Indemnity Group conference, specialists warned that data centre projects can involve unusual contractual, professional and technology-related exposures, especially where contractors rely on annual insurance programs designed for more conventional building work. - read more
Why Mental Health Cover Is Back in the Income Protection Spotlight
29 Oct 2026: Paige Estritori
Australia’s life insurance industry has moved mental health cover back to the centre of the affordability debate, after the Council of Australian Life Insurers released its response on 30 September 2026 to the independent review of the Life Insurance Code of Practice. For workers who rely on income protection insurance, the issue is practical: mental health conditions can affect earning capacity just as seriously as physical illness, but changes designed to keep premiums manageable may also alter what is covered. - read more
Crash Data Shows Where Truck Risk Is Shifting
29 Oct 2026: Paige Estritori
The 2026 National Truck Accident Research Centre major incident report gives Australian truck operators a useful, if challenging, snapshot of where serious heavy vehicle risk is changing. Released in October 2026 and based on de-identified NTI-insured heavy vehicle major-loss claims, the report points to progress on distraction and fatigue, while also highlighting renewed concern about inappropriate speed and following distance. - read more


Professionals Insurance Articles

Why Do Different Professions Need Different Types of Business Insurance?
Business insurance encompasses a range of insurance products designed to protect businesses against financial loss arising from insured events. Depending on the nature of the business, insurance may respond to property damage, legal liability, professional services, cyber incidents, employee-related risks and other operational exposures. - read more
Public Liability Insurance for Professionals Explained
Public liability insurance for professionals can help cover claims that someone was injured or their property was damaged in connection with your business activities. This article explains what it may cover, what it usually does not cover, and how it differs from professional indemnity insurance. - read more
How Policy Limits, Sums Insured and Excesses Work in Professional Insurance
Policy limits, sums insured, sub-limits and excesses affect how much an insurer may pay and how much a professional business may need to contribute if a claim is accepted. Understanding these terms can help Australian professionals compare quotes and policy documents more confidently. - read more
The Importance of Professional Indemnity Insurance for Freelance Professionals
Professional indemnity insurance is a vital safety net for freelance professionals. It is designed to protect individuals offering expert services or advice from claims of negligence or misconduct. Whether you're a consultant, designer, or engineer, having this insurance ensures that you're prepared for unexpected liabilities that could arise from your professional activities. - read more
Understanding the Most Common Types of Business Insurance in Australia
Businesses operate in a wide variety of industries and each faces a different combination of financial, operational, legal and physical risks. Business insurance encompasses a broad range of insurance products designed to respond to different types of insured events, helping businesses manage financial exposures arising from their day-to-day activities. - read more

Knowledgebase
Insurance Premium:
The periodic amount paid for the purchase of insurance.